Property taxes represent one of the largest ongoing expenses homeowners face, yet many property owners lack a clear understanding of how these taxes are calculated, what they fund, or how to manage them effectively. Whether you’re a first-time home buyer or a seasoned property owner, grasping the fundamentals of property taxes can help you budget more accurately and potentially identify opportunities to reduce your tax burden. This guide covers the essential information every homeowner should understand about this significant financial obligation.
How Property Taxes Are Calculated
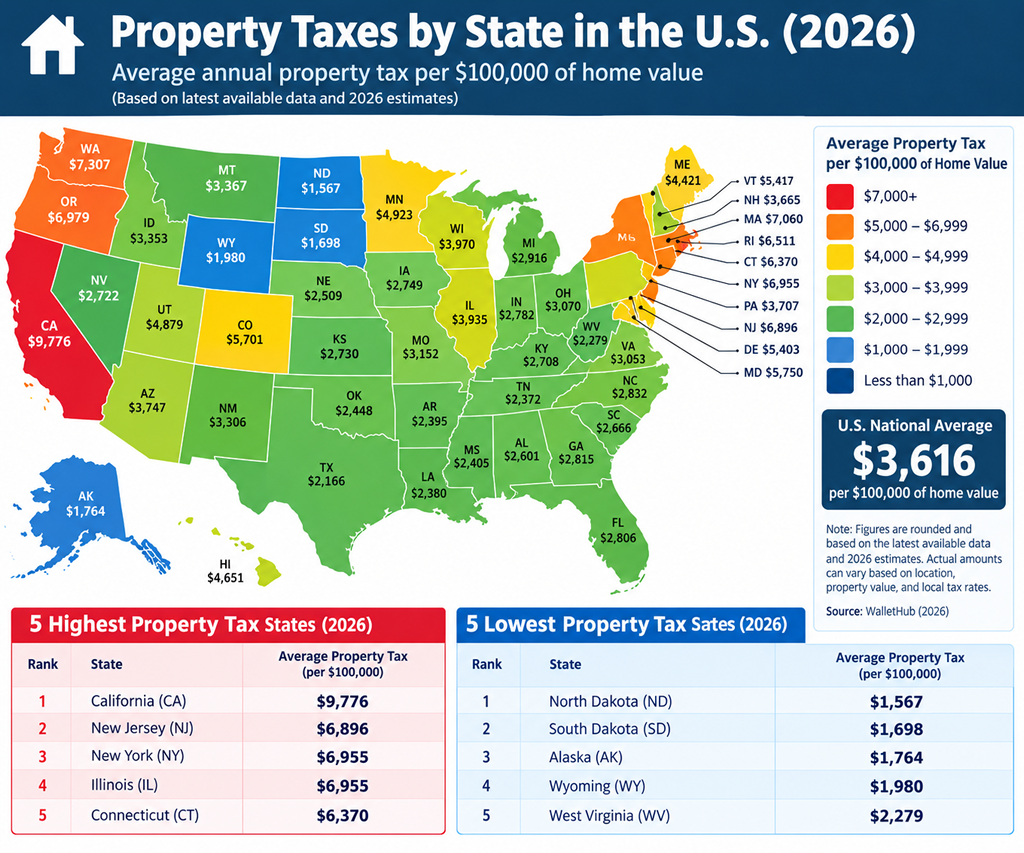
Property taxes are typically calculated using a straightforward formula: the assessed value of your property multiplied by the local tax rate. The assessed value is determined by your local assessor’s office, which evaluates your home based on comparable sales in your area, its physical condition, size, and amenities. The tax rate, often expressed as a percentage or per thousand dollars of assessed value, varies significantly by location and is set by local government bodies. Your county or municipality uses this combination to arrive at your annual property tax bill. Understanding this process helps explain why two similar homes in different areas can have vastly different tax bills. Some regions also adjust assessed values annually, while others reassess properties only periodically.
What Your Property Taxes Fund
When you pay your property taxes, you’re funding essential services and infrastructure in your community. These funds typically support local schools, which represent the largest portion of property tax revenue in most areas. Beyond education, property taxes pay for police and fire departments, road maintenance and construction, public libraries, parks and recreation programs, and administrative services at the county and municipal level. Water and sewer systems also rely heavily on property tax revenue in many jurisdictions. Understanding this connection between your tax payments and community services can provide perspective on the value these taxes represent, even when the bills feel substantial.
Assessment and Appeals
Your local assessor’s office determines the assessed value of your property, but this valuation is not always accurate. Assessments can be based on outdated information, incorrect property descriptions, or flawed comparable sales data. If you believe your property has been over assessed, most jurisdictions allow homeowners to appeal through a formal process, which typically involves submitting recent appraisals, photos of damage or needed repairs, or evidence of lower-assessed comparable properties nearby. Filing an appeal can be time-consuming, but successful appeals often result in lower tax bills that recoup the effort involved. Deadlines vary by location, so check with your local assessor’s office about specific timelines and requirements in your area.
Tax Credits and Exemptions
Many homeowners qualify for property tax credits or exemptions that can significantly reduce their tax burden, yet remain unaware these opportunities exist. Homestead exemptions, available in many states, provide a reduction in assessed value for primary residences, and senior citizens often qualify for additional exemptions or deferrals. Veterans may also receive property tax breaks in recognition of their service, while some states offer credits for low-income homeowners or those who make energy-efficient improvements. Agricultural properties frequently receive special valuation treatment that reflects their use rather than development potential. Researching what your state and locality offer ensures you are not missing out on tax relief you have earned.
Managing Your Property Tax Bill
Effective management of your property taxes starts with understanding your assessment notice and keeping organized records related to your property. Many homeowners pay property taxes through their mortgage lender as part of an escrow account, which means the payment happens automatically each month. If you pay property taxes directly, setting aside funds monthly prevents the shock of a large annual bill and ensures you are prepared when it comes due. When an unexpected tax bill becomes difficult to cover, homeowners who need to bridge a financial gap can rely on residential property tax loans to avoid costly penalties and delinquency. Staying informed about proposed tax rate changes in your community allows you to anticipate increases and adjust your budget accordingly.
Refinancing and Property Tax Implications
If you’re considering refinancing your mortgage, understanding how this decision might affect your property taxes is worthwhile. When you refinance, your lender will typically conduct a new appraisal of your home, and while that appraisal is separate from your tax assessment, a significantly higher value could trigger a reassessment in some jurisdictions. A few states and localities conduct reassessments whenever there is a change in property ownership or major refinancing activity. Before refinancing, contact your local assessor to understand whether this action might trigger a new assessment in your area and potentially increase your tax obligations.
Conclusion
Understanding property taxes empowers homeowners to make informed decisions about their finances and their property. From knowing how assessments are calculated to identifying available exemptions and credits, the knowledge covered in this guide helps you navigate this complex aspect of homeownership more effectively. Taking time to review your assessment, explore tax relief options, and budget for these ongoing obligations ensures you are managing this significant expense as efficiently as possible. By staying informed and proactive, homeowners can work toward reducing their tax burden while supporting the essential services that benefit their communities.